
The Smart Self-Employed Person’s Guide to Year-End Planning
If you run a single-member LLC—or work for yourself in the gig economy—year-end tax planning is key. The “Henssler Money Talks” hosts break down what counts as income, what you can deduct, and strategies for funding a retirement plan before 2025 ends.
Finish the Year Strong by Considering These Tax Moves

2025 is wrapping up fast—and your year-end tax strategy could make a meaningful difference. From maximizing retirement contributions to timing your income, harvesting losses, and making the most of charitable deductions, small steps now can lower your tax bill later.
See How the “One Big Beautiful Bill” Act Will Impact Your 2025 Taxes and Transform Your Financial Landscape!
On July 4th, the President signed into law the so-called “One Big Beautiful Bill” Act (OBBBA), a significant piece of legislation that ushers in a plethora of tax provisions designed to impact taxpayers across the spectrum. Though the act introduces measures that stretch beyond this year, our focus here narrows to changes coming into effect […]
Mid-Year Is More Than a Milestone—It’s a Money Moment
A mid-year review isn’t just about catching up; it’s about getting ahead. The “Henssler Money Talks” experts walk through what you should be reviewing with your adviser now: spending, saving, taxes, investments, and any significant life changes. From rebalancing your portfolio to making smart tax moves, minor adjustments now can make a big difference by year-end.
The Best Time of Year to Take Your RMD? It Depends on Your Goals
The “Henssler Money Talks” show hosts Nick Antonucci, CVA, CEPA, Director of Research, and Managing Associates K.C. Smith, CFP®, CEPA, and D.J. Barker, CWS®, answered key questions from seniors about required minimum distributions (RMDs)—specifically, whether it’s better to take them at the beginning of the year, spread them out over time, or wait until year-end.
2025 Annual Limits Relating to Financial Planning
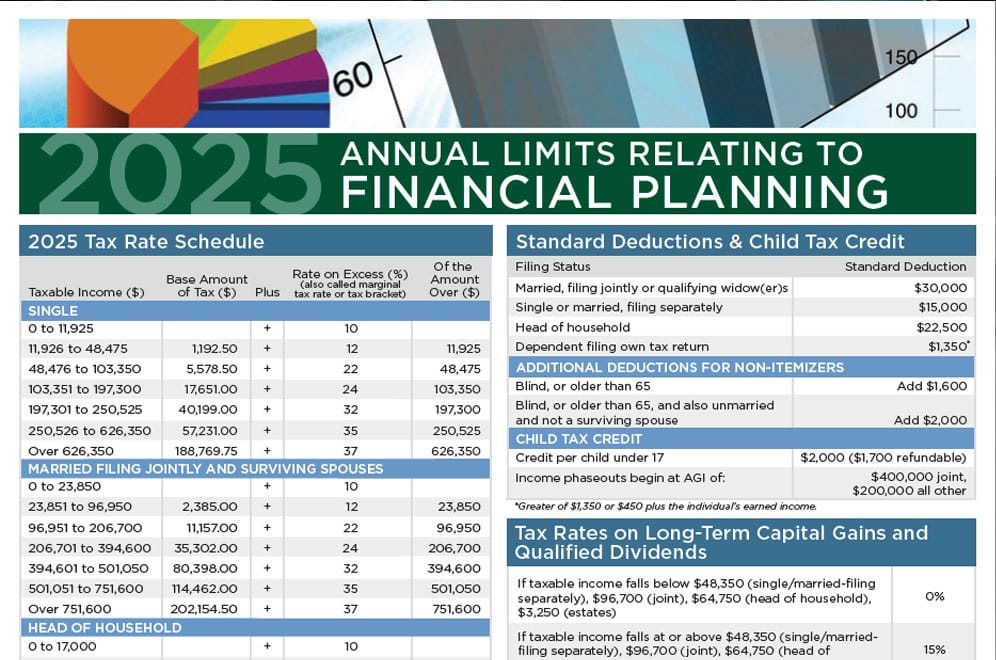
Stay ahead of the game with our handy 2025 Annual Limits Relating to Financial Planning—your go-to resource for all the key numbers and annual limits that impact your financial strategy. This comprehensive PDF includes updated tax brackets, retirement contribution limits, Social Security figures, gifting exclusions, and more.
Financial Safety Nets: Exploring Available Sources of Emergency Funds
When life throws unexpected expenses your way—like medical bills, car repairs, or job loss—having access to emergency funds can make all the difference.
Essential Year End Stock Strategies for Savvy Investors
As the year ends, it’s time to evaluate your stock portfolio and optimize your tax position. Whether it’s offsetting gains with losses, leveraging the 0% capital gains tax rate, or donating appreciated securities, there are many opportunities close the year strong.
Beware: The Dangers of Underpayment Penalties That Could Cost You Big This Tax Season
Did you know the IRS charges an 8% penalty on underpaid estimated taxes in 2024? Managing your estimated payments is critical, especially with fluctuating income or unexpected gains.
How to Prepare for Your Year-End Financial Review: A Guide for SMBs
Wrap up the year strong with a financial check-up for your business! A year-end review is more than a routine task—it’s a chance to boost profitability, improve cash flow, and set the stage for growth in the coming year.